A financial plan has five inputs.
Money. Income. A country. Someone to help you think about all three. And time.
Four of those can be replaced. Money can be earned again. A job can be found again. A country can be left, and a different one chosen. Even the person helping you can be replaced, and sometimes should be.
The fifth cannot be replaced at all.
You cannot get a year back. Not by working harder in the next one. Not by earning more. Not by choosing better the second time around.
That is the whole letter. Everything below is what follows from it.
A year is not a unit of money
It is a unit of the thing money needs in order to do anything useful.
A year buys contribution — one more year of putting something aside, at whatever size you can manage.
It buys length. What a portfolio is able to do is partly a function of how long it is left alone to do it. That is a statement about structure, not about returns, and it holds whether the year is a good one or a bad one.
And it buys evidence about yourself. How you actually behaved in a year when markets fell. What you did when the currency moved against you. How it felt to leave something untouched. That information cannot be bought, borrowed or modelled. It can only be lived through.
Money can be replaced.
A country can be replaced.
A year cannot.
Five ways a year gets spent without a decision
None of these involves carelessness. That is the point of listing them.
01 The year of the move. Shipping, schools, visas, a new bank, a new landlord. Nobody writes a financial plan in a moving year, and nobody should be expected to.
02 The year you waited to see whether the contract would be renewed. A reasonable thing to wait for. It also means the plan was postponed by someone else’s decision, not yours.
03 The year the school decision took all the oxygen. A place was chosen, a fee schedule was accepted, and the household’s horizon quietly changed. That was a financial decision. It just did not feel like one.
04 The year markets fell and waiting felt responsible. It may well have been responsible. That is not the observation. The observation is that the year passed either way.
05 The year nothing in particular happened. No move, no crisis, no decision. These are the easiest years to lose and the hardest ones to notice afterwards.
Each of those is defensible on its own. Added together, they are not a pause in the horizon. They are the horizon.
Why a mobile life loses years differently
A household that stays in one country loses years to ordinary procrastination, and ordinary procrastination is at least visible. You know you are putting something off.
An internationally mobile household loses them to transition instead, which is much harder to see, because every transition year has a legitimate reason attached to it.
The visa runs in cycles. The contract runs in cycles. The lease runs in cycles. There is nearly always something imminent enough to justify waiting until it is settled — and by the time it is settled, the next thing is already imminent.
There is also a quieter version. Many people in this position genuinely do not know how long they will be here. So they treat the whole question as unanswerable and leave it alone. But “how long will I stay” and “what am I planning for” are two different questions. The second one can be answered provisionally. The first one often cannot be answered at all.
An amount is not a length
Most plans specify a number and leave the length blank.
Enough to retire. Enough for the children’s education. Enough to stop thinking about it. Those are amounts. None of them is a date, and an amount with no date attached cannot be tested, funded or adjusted. There is nothing to measure it against.
Here is the part that is arithmetic rather than persuasion. A household that expects the choice to stop being financial at sixty, and is thirty-eight today, has twenty-two years. If nothing is written down until they are forty-one, the same household has nineteen.
Nothing went wrong in that example. No mistake was made and no opportunity was missed. The number simply changed while everyone was busy, which is what numbers do.
What to write down
Not the amount. Not the product. Not a market view. Three dates.
01 The year you would like the choice to stop being financial. Not the year you stop working — the year work becomes optional rather than required.
02 The year your largest existing commitment ends. The mortgage, the last school fee, the lease you have already signed twice.
03 The year the country question has to be answered. A residency renewal, a school transition, a parent who will need someone nearby.
Then measure the distance from today to the nearest of the three.
That distance is your real planning horizon. For many households it is shorter than the one they had been assuming, and that is not a problem to be alarmed about. It is simply the number that was missing.
A goal is an amount.
A horizon is a length.
Most plans have only the first.
One thing this letter is not saying
It is not saying you are late.
Nobody arrives at this with a clean sheet, and a household that has spent fifteen years raising children across three countries has not been wasting the time. They have been using it on something else, and usually on the right something else.
The argument is narrower than that, and it is only this: a year is the one input in a plan that cannot be bought, replaced or recovered — so it is worth knowing how many of them the plan is actually working with, and deciding deliberately what the next one is for.
The Athena Question
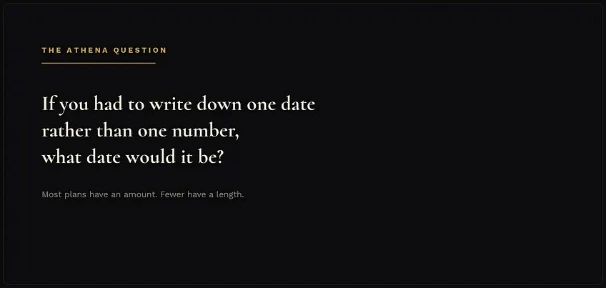
If you had to write down one date rather than one number, what date would it be?
Most plans have an amount. Fewer have a length.
Independent wealth consulting for internationally mobile professionals
@athena_capital_consulting
Cross-border wealth, made clear.